A 25-Basis-Point Hike Was Never the Real Problem
The Fed raising rates by 25 basis points was almost inevitable, and not because the data demanded it.

A 25-Basis-Point Hike Was Never the Real Problem
The Fed raising rates by 25 basis points was almost inevitable, and not because the data demanded it. It was about credibility. A new Fed chair stepping into one of the most politically charged economic environments in recent memory has one job on day one: prove he is not a puppet. That means doing what the role requires, controlling inflation and balancing the broader economy, regardless of what the administration wants.
Trump has had a long and public disagreement with Jerome Powell over rate cuts and inflation management. The expectation with a new chair was that the administration would have more influence over monetary policy. That has not played out. The new chair came in and did exactly what the institution demands. Twenty-five basis points was the signal, not the solution.
Why Rate Hikes Cannot Fix This Particular Problem
Here is what most of the commentary around the Fed misses entirely. The inflationary pressure driving this market right now is energy-driven, and it is being driven by the war with Iran. Raising interest rates does absolutely nothing to oil prices. Nothing. The Fed can move rates all it wants, and the price at the pump stays where the war puts it.
That is the elephant in the room. The broad market is being shaped by an energy-driven inflationary environment that monetary policy cannot touch. And yet the conversation keeps circling back to basis points as if a rate decision in Washington is going to change what is happening in the Middle East.
What Energy Inflation Actually Does to Households
When gas prices rise, the effects move through everyday life in ways that do not show up immediately in the headline numbers. Employees who were comfortable driving 30 to 45 minutes to work are now making real changes to where they live because they cannot afford the commute. That is not a minor inconvenience. That is a shift in where people choose to rent, how far they are willing to travel, and what they are willing to pay for housing.
At the same time, renters are being squeezed from both sides. Household expenses are climbing, borrowing costs are higher, and there is no meaningful rent growth to offset any of it. Operators who were counting on rent increases to cover rising expenses are not going to see that growth. What they are going to see is concessions, zero rent growth, or in some cases negative rent growth. The expenses keep climbing. The revenue does not follow. That gap has to be absorbed somewhere, and there is no bailout coming through the rent line.
What This Means for Commercial Real Estate Right Now
Multifamily transaction volume has been down sharply for the past six to eight months. Brokers, lenders, and operators are under real pressure, and the latest rate hike only makes the math harder. What was underwritten last week is not the same deal this week. A 50- to 60-pip swing in the 10-year Treasury can kill a transaction that looked solid on Monday by Thursday. Even the buffers built into underwriting assumptions have been eaten up by the way the bond market has been moving.
The Maturity Wall and the Can That Has Been Kicked Too Long
Lenders have been extending loans, doing modifications, and working out arrangements with selected operators who have already hit the maturity wall. Some of those situations have been resolved. Many have not. Developers who are now coming to maturity on construction loans are in a particularly difficult position because the rate environment is working directly against them.
The market cannot keep deferring this. The can has been kicked as far as it will go. No one anticipated a war layered on top of already elevated borrowing costs and compressed valuations. That combination, higher rates, lower property values, rising operating expenses, and no rent growth, leaves very little room to maneuver for operators who were already stretched.
Sellers Are Splitting Into Two Groups
Right now, sellers are falling into one of two positions. Those who do not have to sell are pausing, waiting six months to see where the market moves before making a decision. Those who need to sell are not holding out for yesterday's price. They know the market may not improve over the next six to eight months, and their calculation is simple: transact today or lose more tomorrow. That urgency is creating real pricing pressure, and for buyers with liquidity, that is where the opportunity lives.
Where the Opportunity Is for Buyers With Dry Powder
For those sitting on cash right now, this market is producing two specific types of opportunity worth paying attention to. Both involve developers who are under pressure and need to move.
Stabilized Assets Below Replacement Cost
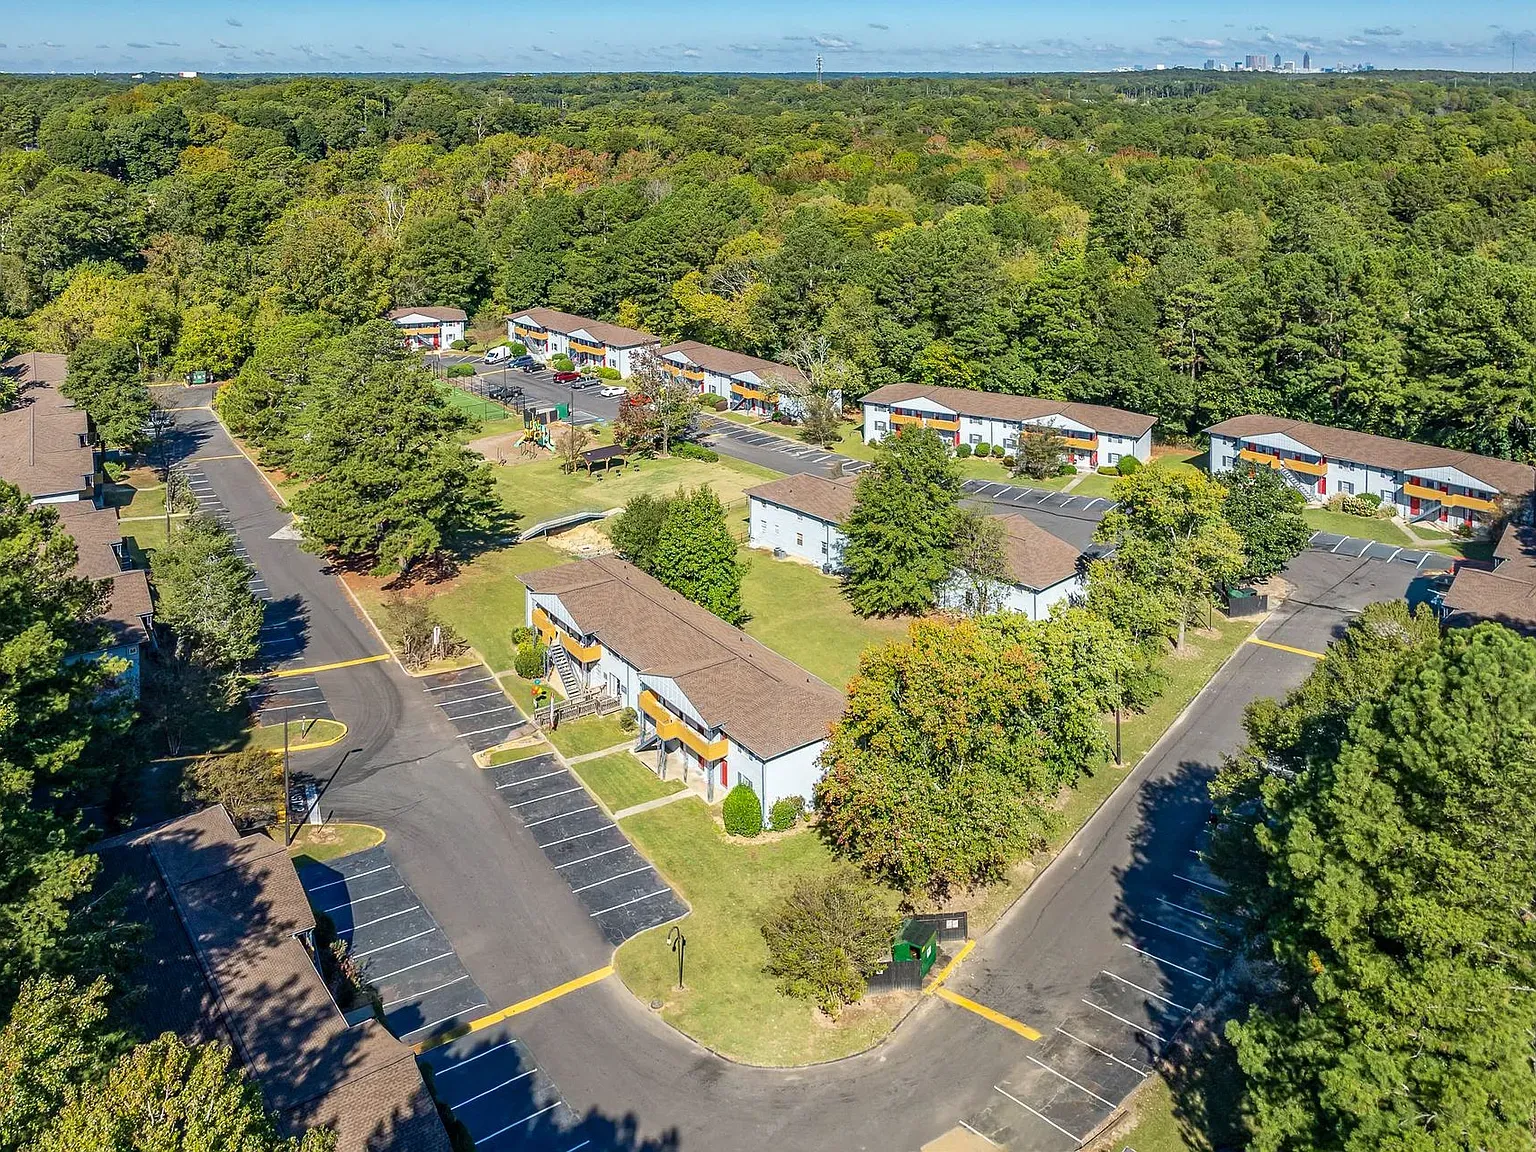
The first opportunity is developers who have already received their certificate of occupancy and have a stabilized asset. These properties can be acquired well below replacement cost. The cost basis available in this environment is genuinely attractive, and that kind of entry point is rare. You are not buying a project in progress. You are buying a finished, operating asset at a price that reflects the seller's distress, not the asset's underlying value.
That gap between distressed price and replacement cost is the margin of safety. It does not guarantee anything, but it gives a buyer real room to work with as the market eventually normalizes.
Near-Complete Projects With Lease-Up Risk
The second opportunity is developers who have not yet received their certificate of occupancy but are 90 to 95 percent complete. A buyer comes in, funds the remaining 5 to 10 percent of the build, takes on the lease-up risk, and stabilizes the asset. There is more risk in this structure than buying a stabilized property, but the entry price reflects that. You are still buying at a significant discount, and the finish line is close.
Both of these scenarios require a buyer who is ready to move and has the capital to do it. That is not most of the market right now. That is exactly why the opportunity exists.
What the Next Rate Decision Is Likely to Look Like
The next Fed move is unlikely to be another 25 basis points. The more probable outcome is 50 basis points. The Fed is going to push aggressively toward its 2 percent inflation target, and given where energy prices are heading because of the war, that target looks like a fantasy. There is no realistic path to 2 percent inflation in an energy-driven inflationary environment that monetary policy cannot influence. But the Fed will try, and a 50-basis-point increase will make an already difficult market harder for operators, developers, and anyone carrying floating-rate debt.
If the war were not a factor, this would be a different conversation. But it is a factor, and it is the dominant one. Rate decisions are secondary to what is happening with energy prices, and energy prices are secondary to what is happening geopolitically. That chain of causation matters for anyone trying to underwrite a deal, plan a hold period, or decide whether to transact now or wait.
If you are sitting on capital and want to talk through where the real opportunities are in this market, reach out to Forja directly. The window for buying distressed assets at a steep discount is open now, and it will not stay open once the market finds its footing.
Stop Speculating. Start Closing.
Apply NowLimited acceptance · By approved application
© 2026 Forja. All rights reserved. - Designed By VAVA Graphics